Mastering Present Bias: Boost Your Retirement Savings by 7%
In the intricate landscape of personal finance, one psychological phenomenon stands out as a formidable barrier to long-term success: overcoming present bias. This pervasive cognitive bias, often referred to as hyperbolic discounting, describes our tendency to favor immediate rewards over larger, delayed rewards. It’s the reason we might splurge on a new gadget today instead of adding to our retirement fund, or choose instant gratification over prudent financial planning. For many, the allure of the present moment can derail even the most well-intentioned savings plans, leading to significant shortfalls in future financial security. But what if there was a way to systematically combat this inherent human tendency and, in doing so, boost your retirement savings by a tangible 7%? This comprehensive guide will delve into the mechanisms of present bias, explore its profound impact on financial decisions, and, most importantly, equip you with actionable strategies to master this bias and secure a more prosperous retirement.
The journey to a financially secure retirement is often envisioned as a straight path, but in reality, it’s fraught with psychological detours. Understanding and actively working against present bias is not just an academic exercise; it’s a practical necessity for anyone serious about their financial future. The promise of a 7% increase in retirement savings isn’t an arbitrary figure; it represents a significant, achievable improvement that can compound dramatically over decades. This article will provide the framework, the tools, and the motivation to make that increase a reality. We will explore the behavioral economics behind why we struggle with long-term planning and then pivot to powerful, evidence-based strategies that empower you to prioritize your future self without feeling deprived in the present.
What is Present Bias and Why Does It Matter for Your Retirement?
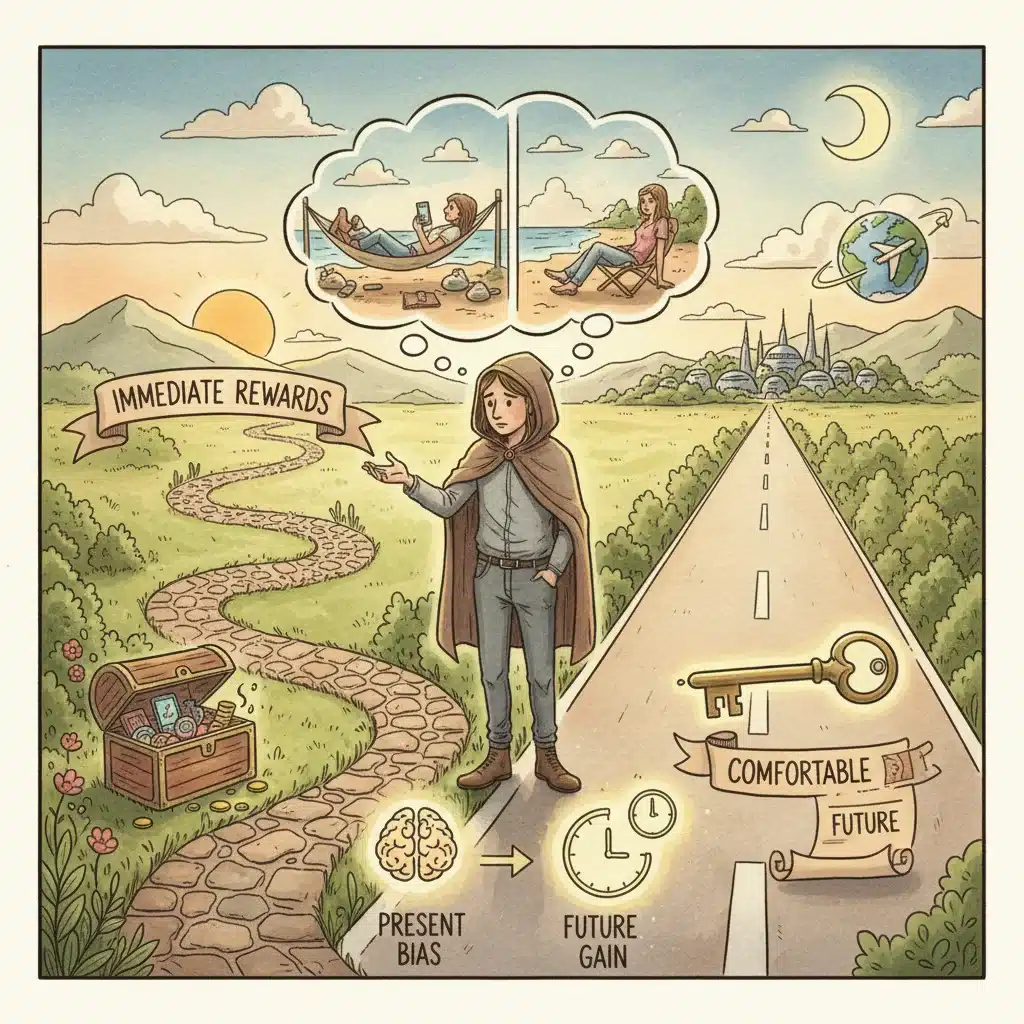
At its core, overcoming present bias involves recognizing and mitigating our innate preference for immediate gratification. Imagine being offered $100 today or $110 in a month. Many would choose the $100 today, even though waiting a short period yields a higher return. This illustrates the fundamental challenge. When it comes to retirement savings, the ‘reward’ is decades away, making it incredibly difficult for our brains, which are wired for survival and immediate satisfaction, to prioritize it over current desires. This cognitive quirk isn’t a sign of weakness; it’s a fundamental aspect of human psychology, one that financial institutions and marketers often exploit.
For retirement planning, the implications are severe. Every dollar spent today is a dollar not saved for tomorrow, and more importantly, a dollar that won’t benefit from the power of compound interest over many years. A small, seemingly insignificant decision to delay saving or to reduce contributions can lead to a substantial difference in your nest egg by the time you reach retirement age. The cumulative effect of consistently choosing present consumption over future investment is often underestimated. This is why addressing present bias isn’t merely about saving more; it’s about fundamentally altering your financial decision-making framework to align with your long-term goals.
The challenge intensifies because the future feels abstract. Our ‘future self’ often feels like a stranger, making it harder to make sacrifices for them. Behavioral economists have shown that we often treat our future selves as if they were different people entirely. This psychological distance makes it incredibly difficult to connect current actions with future outcomes. Therefore, effective strategies for overcoming present bias must bridge this gap, making the future more vivid and the present sacrifices more palatable.
The Impact of Present Bias on Your Financial Health
The ripple effects of present bias extend far beyond just retirement savings. It influences debt accumulation, emergency fund creation, investment decisions, and even career choices. When present bias dominates, individuals are more likely to take on high-interest debt for immediate purchases, neglect building an emergency fund, or shy away from long-term, growth-oriented investments in favor of safer, but lower-return, short-term options. This creates a vicious cycle where immediate gratification leads to financial instability, which in turn makes it even harder to save for the future.
Consider the average person’s financial journey. They might start with good intentions, perhaps even setting up an initial retirement contribution. However, when faced with an unexpected expense or a tempting offer, the future self takes a back seat. The ‘just this once’ mentality becomes a regular occurrence, slowly eroding the foundation of their financial plan. This isn’t a failure of willpower in isolation; it’s a testament to the powerful, often subconscious, pull of the present. Understanding this dynamic is the first step towards overcoming present bias effectively.
Studies have consistently shown that individuals who struggle with present bias tend to have lower net worth, higher debt levels, and greater financial stress in their later years. The cumulative impact of these small, present-focused decisions can be devastating. Conversely, those who successfully manage this bias are often characterized by robust savings, lower debt, and greater financial freedom. The good news is that this isn’t an unchangeable trait; it’s a cognitive bias that can be systematically addressed and managed with the right strategies and tools.
Strategy 1: Automate Your Savings and Investments
One of the most powerful and widely recommended strategies for overcoming present bias is automation. By setting up automatic transfers to your retirement accounts, you remove the need for conscious decision-making each pay period. This ‘set it and forget it’ approach leverages inertia in your favor. Once the money is automatically directed to savings, it’s out of sight and out of mind, significantly reducing the temptation to spend it on immediate gratification.
Many employers offer direct deposit options where a portion of your paycheck can go directly into a 401(k) or other retirement plan. If not, you can set up automatic transfers from your checking account to an IRA or brokerage account on a regular schedule – weekly, bi-weekly, or monthly. The key is consistency and making these transfers non-negotiable. Start with an amount that feels manageable, even if it’s small, and then commit to increasing it over time.
Consider the ‘pay yourself first’ principle. Before you pay any bills or indulge in discretionary spending, ensure your savings contributions are made. This prioritizes your future self and makes saving a primary expense rather than an afterthought. This strategy is particularly effective because it bypasses the daily internal debate that present bias thrives on. When the decision is made once and then executed automatically, you effectively disarm the bias before it can influence your choices.
Strategy 2: Visualize Your Future Self and Goals
As mentioned earlier, our future selves often feel distant and abstract. A potent strategy for overcoming present bias is to make your future self and your retirement goals more concrete and vivid. This can involve various visualization techniques designed to bridge the psychological gap between your present and future self.
One effective method is to create a ‘future self’ portrait. This isn’t just imagining; it’s actively detailing what your life will look like in retirement. Where will you live? What activities will you pursue? Who will you spend time with? What does your financial freedom feel like? Write it down, create a vision board, or even use age-progression apps to see what you might look like in 20 or 30 years. Regularly reviewing these visualizations can create a stronger emotional connection to your future, making present sacrifices feel more meaningful.
Another powerful visualization technique is to quantify your goals. Instead of just ‘saving for retirement,’ aim for ‘saving $X by age Y to afford Z lifestyle.’ Breaking down large, distant goals into smaller, more manageable milestones can also help. For example, focus on saving an extra $100 this month, knowing it contributes to your larger vision. This makes the progress tangible and reinforces the link between your current actions and your desired future. The more real and appealing your future self becomes, the easier it is to make decisions that benefit them.
Strategy 3: Implement the ‘Commitment Device’ Approach
Commitment devices are pre-commitments to a future course of action that are designed to make it costly (either financially or psychologically) to deviate from that course. They are excellent tools for overcoming present bias because they remove future choices from the realm of immediate temptation.
For financial planning, a simple commitment device could be setting up an automatic savings plan with a penalty for early withdrawal (e.g., certain types of CDs or investment accounts). Another example is publicly declaring your financial goals to friends or family. The social pressure to follow through can be a powerful motivator. Some apps and services even offer commitment contracts where you pledge to meet a goal and, if you fail, you forfeit money to a charity you dislike or to a friend.
Consider the concept of ‘save more tomorrow’ programs. These programs ask individuals to commit today to increasing their savings rate in the future, often tied to salary raises. This cleverly leverages two psychological insights: people are more willing to save future income than current income, and they are less likely to feel the pinch of increased contributions when it coincides with a pay raise. By making these commitments in advance, you lock in future positive financial behavior, effectively outsmarting your future self’s potential present bias.
Strategy 4: Leverage Behavioral Nudges and Framing
Behavioral nudges are subtle interventions that guide people towards better decisions without restricting their choices. Framing, on the other hand, involves presenting information in a way that influences how it’s perceived. Both can be powerful in overcoming present bias.
One effective nudge is making the default option the desired behavior. For instance, automatic enrollment in 401(k) plans, where employees have to actively opt-out rather than opt-in, has significantly increased participation rates. If your employer offers this, embrace it. If not, consider making your automatic savings contributions the ‘default’ and treat any remaining money as your disposable income.
Framing can also play a crucial role. Instead of viewing saving as a sacrifice, frame it as an investment in your future freedom, peace of mind, or dream retirement. For example, instead of thinking, ‘I can’t buy that new coffee maker because I have to save,’ reframe it as, ‘By not buying that coffee maker, I’m buying myself an extra day of retirement freedom.’ Focusing on the positive future outcome can make the present sacrifice feel less like deprivation and more like empowerment.
Strategy 5: Set Specific, Achievable, and Time-Bound Goals
Vague goals often fall prey to present bias. When your financial objectives are ill-defined, it’s easy to postpone action. For overcoming present bias, it’s essential to set SMART (Specific, Measurable, Achievable, Relevant, Time-bound) goals. Instead of ‘I want to save more for retirement,’ aim for ‘I will increase my 401(k) contributions by 2% of my salary starting next month, aiming for an additional $1,500 by the end of the year.’
Breaking down your overall retirement savings goal into smaller, more manageable milestones can make the journey less daunting. For example, if your ultimate goal is to save $1 million, set interim goals like ‘save an additional $10,000 this year’ or ‘increase my contribution rate by 1% every six months.’ Each time you hit a milestone, you get a sense of accomplishment, which provides positive reinforcement and strengthens your resolve to continue.
Regularly review your progress against these goals. This not only keeps you accountable but also allows you to make adjustments as needed. Seeing tangible progress can be a powerful antidote to present bias, as it makes the future rewards feel closer and more attainable. Celebrate small victories along the way; this helps to associate positive emotions with your long-term financial journey.
Strategy 6: Create a ‘Financial Buffer’ for Impulses
Sometimes, the pull of present gratification is simply too strong to ignore entirely. Rather than fighting every impulse, a practical strategy for overcoming present bias is to create a designated ‘financial buffer’ for controlled indulgence. This involves allocating a small portion of your budget specifically for discretionary spending or immediate wants, while ensuring your long-term savings remain untouched.
Think of it as a ‘fun money’ fund. By consciously setting aside a modest amount for immediate pleasures, you can satisfy some of your present desires without derailing your entire financial plan. This approach acknowledges the reality of human behavior rather than trying to completely suppress it. It allows for a healthy balance, preventing feelings of deprivation that can often lead to larger, more damaging financial binges later on.
The key here is discipline within the buffer. Once the ‘fun money’ is spent, it’s spent. You don’t dip into your retirement savings or emergency fund to cover additional immediate wants. This strategy helps train your brain to separate immediate gratification from long-term financial security, fostering a more sustainable approach to wealth building. It’s about moderation and conscious allocation, not complete denial.
Strategy 7: Seek Professional Financial Guidance
For many, navigating the complexities of financial planning, especially while battling inherent biases, can be overwhelming. Seeking advice from a qualified financial advisor can be an invaluable strategy for overcoming present bias. A professional can provide an objective perspective, help you set realistic goals, and create a structured plan tailored to your unique circumstances.
A financial advisor can act as an external commitment device, holding you accountable to your long-term goals. They can help you identify areas where present bias might be impacting your decisions, offer strategies to mitigate it, and provide the expertise to optimize your investment portfolio. Their guidance can be particularly beneficial in making the abstract future concrete by showing you projections of your retirement savings under different scenarios.
Furthermore, a good advisor can educate you on the power of compounding and the true cost of delaying savings, making the long-term benefits of present sacrifices more apparent. They can help you set up automated systems and review your progress regularly, ensuring you stay on track. While there is a cost associated with financial advice, the long-term benefits, especially in terms of increased savings and reduced financial stress, often far outweigh the fees.
The 7% Advantage: How These Strategies Lead to Growth
Now, let’s address the promised 7% increase in retirement savings. This isn’t a magic number but a realistic and achievable target when you consistently apply the strategies for overcoming present bias. How does it break down?
- Reduced Impulsive Spending: By recognizing and mitigating present bias, you’ll naturally reduce impulsive purchases that drain your immediate funds. Even small, frequent impulsive buys add up. Redirecting just a fraction of this saved money to retirement can easily account for a 1-2% increase in your annual savings rate.
- Increased Automatic Contributions: Implementing automation makes it effortless to save more. Committing to even a 1% increase in your 401(k) contribution each year, especially when coupled with a raise, significantly boosts your savings. Over time, these consistent increases can easily add another 2-3% to your overall growth.
- Optimized Investment Decisions: With a long-term perspective fostered by overcoming present bias, you’re more likely to make sound investment decisions, such as diversifying your portfolio and staying invested during market fluctuations. Avoiding emotional, short-term reactions can lead to better returns, potentially adding another 1-2% in growth.
- Avoidance of High-Interest Debt: Present bias often leads to taking on high-interest credit card debt. By avoiding this debt, you free up substantial funds that would otherwise go to interest payments, allowing you to direct those savings towards retirement. This indirect saving can contribute another 1% or more to your overall financial health, effectively boosting your retirement potential.
- Consistency and Compounding: The most significant impact comes from the consistent application of these strategies. By regularly prioritizing your future self, you allow the power of compound interest to work its magic uninterrupted. A consistent 7% improvement in your annual savings or investment performance, compounded over 20-30 years, results in a dramatically larger retirement fund than you might initially imagine.
The 7% isn’t just about saving more cash; it’s about optimizing your entire financial ecosystem by making smarter, future-oriented decisions. It’s a combination of direct savings, avoided costs, and improved investment performance, all stemming from a disciplined approach to overcoming present bias.
Putting It All Together: Your Action Plan
Overcoming present bias is not a one-time event; it’s an ongoing process that requires conscious effort and strategic implementation. Here’s an action plan to help you integrate these strategies and achieve your 7% retirement savings boost:
- Assess Your Current Situation: Understand where present bias is most affecting your finances. Track your spending for a month to identify impulsive purchases.
- Automate Aggressively: Set up automatic transfers to your 401(k), IRA, or other investment accounts. Aim to increase your contribution rate by at least 1% immediately, and commit to another 1% increase with your next raise.
- Visualize Your Future: Dedicate time to truly define and visualize your retirement goals and your future self. Keep these visualizations prominent.
- Implement a Commitment Device: Whether it’s telling a friend about your goals or using an app, find a way to make it harder to deviate from your savings plan.
- Frame Your Choices Positively: Reframe saving as an act of empowerment and freedom, not deprivation.
- Set SMART Milestones: Break down your large retirement goal into smaller, achievable, and time-bound targets. Track your progress regularly.
- Create a ‘Fun Money’ Buffer: Allocate a small, controlled amount for immediate gratification to prevent larger financial derailments.
- Consider Professional Help: If you feel overwhelmed, consult a financial advisor to help you build and maintain your plan.
Remember, every small step you take today to combat present bias is a significant leap towards a more financially secure and fulfilling retirement. The 7% increase is not just a number; it’s a testament to the power of informed decision-making and consistent action against our inherent psychological tendencies. Your future self will thank you for the foresight and discipline you cultivate today.
Conclusion: A Future Forged in the Present
The battle against present bias is one of the most critical challenges in personal finance. Our natural inclination towards immediate rewards can sabotage even the best intentions for long-term financial security. However, by understanding this powerful psychological force and implementing deliberate, evidence-based strategies, you can not only mitigate its negative effects but also harness its counter-forces to your advantage. The strategies outlined in this article – from automation and visualization to commitment devices and professional guidance – provide a robust framework for overcoming present bias.
The goal of boosting your retirement savings by 7% is an ambitious yet entirely achievable objective. It represents a significant shift in financial behavior, a commitment to your future self, and a mastery over one of humanity’s most pervasive cognitive biases. Imagine the peace of mind, the freedom, and the opportunities that an additional 7% growth compounded over decades can afford you in retirement. This isn’t just about accumulating wealth; it’s about building a life of greater security, choice, and fulfillment.
Start today. Don’t let the allure of the present moment steal from your future. Take concrete steps, no matter how small they seem, to align your financial actions with your long-term aspirations. The journey to a prosperous retirement begins with a single, conscious decision to prioritize your future self. By mastering present bias, you are not just saving money; you are investing in a better, brighter tomorrow.